
When a business expands across borders, one of the first operational questions that surfaces is not about products or logistics — it is about financial oversight. Who will manage compliance? Who understands local tax structures well enough to prevent costly errors? Who has the institutional depth to handle audits, transfer pricing, and regulatory reporting simultaneously?
These are not abstract questions. They affect cash flow timelines, investor confidence, and regulatory standing in real, measurable ways. For companies operating in or entering the Indian market, the choice of accounting partner carries particular weight. India’s regulatory environment — shaped by the Institute of Chartered Accountants of India, the Companies Act, and GST compliance requirements — demands firms that understand local nuance as well as global standards.
This breakdown examines the world’s leading accounting firms alongside India’s strongest domestic and regional players. The goal is not to declare a winner, but to give decision-makers a clearer picture of what each tier actually offers and where the differences are most consequential.
What Separates Global Accounting Firms from Regional Ones
The distinction between global and regional accounting firms is not simply about size. It is about infrastructure, service scope, and the ability to operate consistently across jurisdictions with different legal, tax, and reporting frameworks. Global firms maintain standardized methodology across offices, which means a client in Mumbai receives advisory built on the same technical foundation as one in Frankfurt or Toronto. That consistency has real value when cross-border transactions, international audits, or multi-country tax planning are involved.
For businesses evaluating their options, reviewing curated directories of top accounting firms — such as those profiling India-based practices across audit, tax, and advisory — offers a useful starting point for understanding how domestic firms position themselves within the global framework. Regional firms, by contrast, often carry advantages that global networks cannot replicate: depth in local compliance, faster turnaround on statutory filings, and stronger relationships with domestic regulatory bodies.
The choice is rarely binary. Many mid-market companies retain a regional firm for day-to-day compliance and engage a global firm for specific transactions or international reporting requirements. Understanding where each type of firm performs best is the foundation for making that decision well.
How Global Firms Maintain Consistency Across Markets
Global accounting networks — often structured as alliances of legally independent member firms — invest heavily in shared methodology, training protocols, and audit standards. This is what allows a multinational to present consolidated financials that satisfy regulators in multiple countries without rebuilding the process from scratch in each market.
The practical implication is that a global firm brings a replicable system, not just experienced professionals. That system includes quality control reviews, documentation standards, and risk assessment frameworks that apply uniformly. For companies with complex ownership structures or entities in multiple jurisdictions, this reduces the risk of inconsistency between subsidiaries’ financial reporting — a risk that can create significant problems during due diligence or regulatory examination.
Where Regional Firms Hold a Structural Advantage
Regional and domestic firms are built around the specific statutory and tax environment of their home market. In India, this means deep familiarity with GST filing timelines, provisions under the Income Tax Act, Companies Act compliance for private and listed entities, and the expectations of the Registrar of Companies. These are not areas where general global expertise substitutes well for local operational knowledge.
Beyond technical knowledge, regional firms often maintain closer working relationships with the officials and departments that handle registrations, assessments, and appeals. Response times on domestic filings, rectifications, and notices tend to be faster when the firm has established communication channels with the relevant authorities. For small to mid-sized businesses that do not require cross-border services, this practical advantage often outweighs the brand recognition of a global network.
The World’s Largest Accounting Firms and What They Actually Do
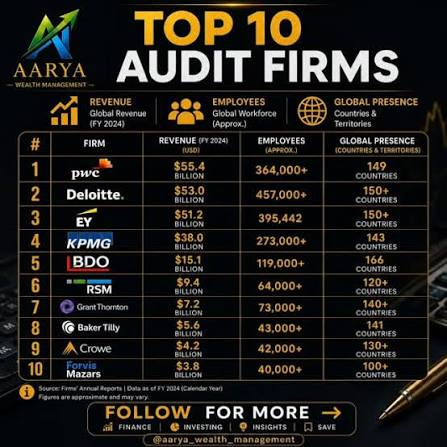
The firms commonly referred to as the Big Four — Deloitte, PricewaterhouseCoopers, Ernst and Young, and KPMG — dominate global audit and advisory work by a significant margin. Each operates across more than a hundred countries and handles audits for the majority of the world’s largest publicly listed companies. Their scale is not incidental; it is a product of decades of acquisitions, international expansion, and standardization of service delivery.
Beyond the Big Four, firms such as Grant Thornton, BDO, RSM, Mazars, Crowe, and Baker Tilly make up what is broadly termed the second tier of global accounting networks. These firms serve large mid-market companies and, in some cases, publicly listed entities that prefer a less centralized audit relationship. Their reach is global, but their client profile tends to differ — more privately held businesses, more sector-specific advisory, and often more direct partner involvement in engagements.
Big Four Operations in India
All four of the largest global accounting firms operate in India through affiliated or associated entities. Under Indian law and the regulations of the Institute of Chartered Accountants of India, foreign accounting firms cannot directly practice statutory audit in India. Instead, they operate through Indian affiliate firms that hold the necessary licenses, while the global network provides methodology, training, and cross-border support.
This structure matters for clients. The Indian affiliates of global firms handle statutory audits, tax advisory, and transaction support under Indian regulatory frameworks, while drawing on global resources for international engagements. The arrangement works well for large Indian corporates with foreign investors or overseas subsidiaries, but the layered structure can sometimes slow responsiveness for straightforward domestic compliance work.
Second-Tier Global Firms and Their India Presence
Firms like Grant Thornton Bharat, BDO India, and RSM India have built substantial practices in the country, often serving listed and unlisted companies that want robust audit quality without the overhead associated with a Big Four engagement. These firms tend to be more flexible in terms of engagement structure and often compete effectively for mid-market mandates where relationship depth and sector knowledge matter as much as global brand recognition.
For Indian companies planning an overseas listing or international acquisition, these second-tier global firms can offer a credible bridge — recognized by foreign investors and regulators, but operationally embedded in the Indian market in a way that supports day-to-day compliance without friction.
India’s Strongest Domestic Accounting Firms
India has a robust domestic accounting profession, anchored by firms that have grown independently of global networks and built strong reputations across audit, taxation, and advisory services. Firms such as S.R. Batliboi and Co., Lodha and Co., Kalyaniwalla and Mistry, Nangia and Co., and several others have established practices spanning decades, with client rosters that include public sector undertakings, listed companies, and high-growth private businesses.
According to the Institute of Chartered Accountants of India, there are over three hundred thousand practicing chartered accountants in India, making it one of the largest professional accounting bodies in the world. The depth of that professional pool supports a wide range of independent firms with genuine technical capability across all major service areas.
Strengths of Homegrown Indian Accounting Practices
Domestic Indian firms carry several structural advantages that are easy to underestimate. Their teams are built around Indian statutory requirements from the ground up, which means partners and managers are not applying globally standardized methodology to local situations — they are working from frameworks designed specifically for Indian conditions. This reduces interpretation gaps, speeds up filings, and generally results in fewer errors during complex domestic transactions.
Many of India’s established domestic firms also have deep sector expertise — particularly in manufacturing, real estate, financial services, and pharmaceuticals — that reflects decades of work in those industries within the Indian context. For companies operating in regulated sectors, that accumulated knowledge is not easily replicated by a global firm staffing an Indian engagement from a generalist team.
Limitations to Consider with Domestic-Only Practices
Where domestic Indian firms face genuine limitations is in cross-border work. Transfer pricing documentation for multinational structures, international GAAP reconciliation, and coordination with foreign auditors for consolidated reporting all require either a global network affiliation or specialized teams with international exposure. Without those resources, domestic firms may be able to handle the Indian portion of an engagement competently but cannot extend services across jurisdictions in a coordinated way.
This is not a criticism of domestic firm quality — it reflects the operational reality of how international financial reporting works. A company choosing a domestic-only firm should be clear about where the boundary of that firm’s service scope sits, and whether that boundary creates gaps in its overall compliance posture.
Matching Firm Type to Business Need
The practical question for any business is not which firm is objectively better, but which firm is structurally suited to the work that actually needs to be done. A family-owned manufacturing business with operations entirely within India does not benefit meaningfully from a global network that serves multinational corporations. Conversely, an Indian startup raising international venture funding and planning an overseas listing needs advisors who can operate in both regulatory environments simultaneously.
Service scope, sector experience, geographic reach, and engagement model all shape which firm type is appropriate. The right answer changes as a business grows, as ownership structures evolve, and as transaction complexity increases. This is why many companies reassess their accounting relationships at significant inflection points — a new round of funding, an acquisition, a regulatory change — rather than treating the relationship as a fixed arrangement.
Cost Structure and Engagement Expectations
Global firms, particularly at the Big Four level, carry fee structures that reflect their overhead, methodology infrastructure, and partner-to-staff ratios. For businesses that do not require that level of infrastructure, the cost differential relative to a well-qualified domestic or second-tier firm is often difficult to justify. Smaller companies frequently find that strong domestic or mid-tier firms deliver equivalent technical output on straightforward engagements at significantly lower cost.
Engagement expectations also differ. Global firms typically work through structured teams with defined roles, formal documentation requirements, and standardized communication protocols. Domestic firms often offer more direct access to senior professionals and faster informal communication. For companies where responsiveness and relationship continuity matter as much as methodology, this operational difference is relevant.
Conclusion
The global versus India comparison in accounting is not a question of which tier is superior — it is a question of fit. Global firms offer consistency, cross-border capability, and institutional credibility that matters in certain contexts. India’s domestic and regional firms offer local depth, regulatory familiarity, and practical accessibility that serves a different but equally real set of needs.
What the comparison ultimately reveals is that the accounting profession, both globally and within India, is more varied and specialized than a simple ranking suggests. The Big Four dominate large-cap audit by volume and brand, but they do not hold a monopoly on quality or technical depth. India’s strongest domestic firms have earned their standing through sustained performance in a demanding regulatory environment, and that standing deserves serious consideration from any business operating primarily within the country.
Decision-makers would benefit most from evaluating potential firms against their actual compliance requirements, geographic footprint, transaction history, and growth trajectory — rather than defaulting to either global brand recognition or lowest available fee. That evaluation, done carefully, tends to produce more stable and productive long-term advisory relationships than either shortcut alone.